Author: Andy Mohr Honda Team
Deciding how to pay for your new Honda is just as critical as choosing all-wheel drive for snowy Indiana winters. Whether you buy a CR-V for trips to Lake Monroe or lease a Civic for your 17-minute commute to the Indiana University campus, comparing financing and leasing helps balance your budget.
Andy Mohr Honda has established a long-standing presence in the community, serving as a reliable, long-term automotive partner for drivers in Bloomington, IN, and nearby areas like Columbus, Greenwood, Bedford, and Terre Haute. Combining trusted experience with local knowledge, we explicitly highlight our expertise in servicing and maintaining Honda vehicles for the road ahead.
Key Takeaways (TL; DR)
Whether you're eyeing a fuel-efficient Civic for commuting to the Indiana University campus or a versatile CR-V to haul gear out to Lake Monroe, securing the right payment plan is essential. Understanding the fundamentals of auto loans and leases helps Bloomington drivers confidently navigate their financing options and lock in terms that comfortably fit their daily lives.
- Your Credit Score Drives the Rate: Your financial history directly influences the annual percentage rate (APR) you qualify for on a loan or lease. A strong credit rating usually translates to lower interest charges over the life of your contract.
- Honda Financial Services Streamlines the Process: Getting pre-approved through Honda Financial Services (HFS) can simplify your paperwork. HFS frequently extends competitive rates and flexible term lengths—ranging from 24 to 72 months on models like the Accord—so you know your purchasing power before heading down State Road 46.
- Financing vs. Leasing: Buying a vehicle means you build equity over time until you own it outright. On the flip side, leasing is similar to a long-term rental and includes annual mileage limits (often 10,000 to 15,000 miles); if your daily driving mostly consists of short hops around College Mall and downtown Bloomington, a lease often provides a lower monthly payment.
- Lease-End Flexibility: When your contract concludes, you have multiple avenues to explore. You can purchase the Honda you've been driving, return it to lease a brand-new model, or simply turn in the keys if your transportation needs have changed.
- Exclusive Savings Programs: Eligible shoppers can reduce their overall costs through targeted incentives. Programs such as the Honda College Graduate Bonus or the Honda Military Appreciation Offer provide tangible financial benefits to those who meet the criteria.
- Preparation Pays Off: Assembling crucial documents—like a valid driver's license, proof of insurance, and recent income statements—prevents delays. Setting a realistic budget ahead of time ensures your next vehicle easily fits into your personal finances.
How Financing Your Honda Actually Works
When you choose automotive financing, you are taking out a loan to cover the upfront purchase price of your vehicle, which you repay over a set schedule known as the loan term. For drivers in Bloomington, this often means securing funds through a local credit union or Honda Financial Services to bring home a model like the 2027 Honda CR-V. Auto loan terms typically range from 36 to 72 months, dictating exactly what you owe each month as you commute down State Road 46 or navigate around the Indiana University campus. Understanding these timelines matters because opting for a shorter term increases your monthly bill, but it significantly reduces the total interest you pay over the life of the loan.
As you make those scheduled payments, you actively build equity, which is the actual cash value of the vehicle that belongs entirely to you. For example, if you finance a 2027 Honda Civic and pay down $10,000 of the principal balance, that is $10,000 of hard equity you can eventually use toward a future trade-in. Once you submit your final payment, the lender officially transfers the car's title into your name, leaving you with full ownership. This route is ideal if you want to rack up unlimited mileage driving out to Hoosier National Forest for weekend hikes, or if you plan to keep your vehicle long after the standard 3-year/36,000-mile Limited Vehicle Warranty expires.
How Honda Financial Services Works

Securing the keys to a 2027 Honda CR-V Hybrid or an efficient Civic Sedan shouldn't feel complicated. Honda Financial Services acts as the brand’s official in-house lender, directly linking buyers with competitive loan and lease programs tailored to specific models. For drivers navigating the busy corridors around Bloomington, this streamlined process means less time stressing over paperwork and more time enjoying the weekend drive down State Road 46 toward Lake Monroe.
The financing journey easily starts before you even commute past College Mall Road. By utilizing the online pre-approval system, you can securely submit your application from home to get a firm grasp on your purchasing power. Dealership teams then collaborate directly with Honda Financial Services to review your credit history, income, and desired structure—helping you seamlessly weigh options like a traditional 60-month finance term versus a flexible 36-month lease.
Keep in mind that final rates, promotional Annual Percentage Rates (APRs), and available terms will always vary based on your personal credit profile. For example, if you are a young professional starting a career near the Indiana University campus, factoring in brand-specific graduate programs or returning-customer loyalty bonuses can noticeably lower your monthly out-of-pocket costs compared to standard third-party bank loans.
How Does Leasing a New Honda Work?
Think of a Honda lease as a flexible, long-term arrangement—typically lasting 24 to 36 months—where you pay only for the portion of the vehicle you actually use. Rather than financing the entire purchase price of a new Civic or CR-V, your monthly payments cover the car’s depreciation. This is simply the difference between its original sticker price and its estimated "residual value" at the end of your contract. Alongside this depreciation, lease payments include taxes, standard setup fees, and a "money factor," which operates as the leasing industry's version of an interest rate. What this means for Bloomington drivers is that you avoid the long-term commitment of ownership while keeping your transportation budget predictable as you commute to the Indiana University campus or run daily errands down State Road 46.
This financial structure creates a distinct contrast: if you take out a traditional loan, you are financing the car's full value, but with a lease, you are essentially funding just the value it loses over a few years. Most standard Honda lease agreements also align neatly with the New Vehicle Limited Warranty of 3 years or 36,000 miles, ensuring unexpected powertrain or component repairs are generally covered during your time with the vehicle. Drivers simply select an annual mileage limit—usually between 10,000 and 15,000 miles—that matches their routine, whether that involves staying close to downtown or packing up for weekend trips out to Lake Monroe.
What Are Your Choices When a Honda Lease Ends?
Approaching the end of a typical 36-month Honda lease opens up three distinct paths. For drivers around Bloomington, what this means is you have the flexibility to adapt to your changing lifestyle, whether you want to keep the car you already know or grab the keys to a brand-new model. If commuting along State Road 46 has made you appreciate your current CR-V, buying it outright might be your smartest financial move. On the flip side, you can effortlessly swap it for a newer ride or simply hand it back after a standard inspection.
- Purchase Your Leased Honda: If your current vehicle has been the perfect companion for hauling weekend gear out to Lake Monroe, you can just buy it. You will pay the residual value established in your original contract, letting you skip the stress of fluctuating market prices on sites like Kelley Blue Book.
- Lease or Finance a New Vehicle: Sometimes you just want the latest engineering or safety technology. You can turn in your current car and seamlessly roll into a new lease or purchase agreement, perhaps upgrading from a compact Civic sedan to a more spacious Passport SUV.
- Return It and Walk Away: You always have the option to close out your contract and return the vehicle without committing to another one. To avoid surprises, schedule a complimentary end-of-lease inspection roughly 60 days before your final date. Fixing a minor dent or replacing worn tires yourself before this inspection often costs far less than a wear-and-tear penalty at turn-in.
Financing vs. Leasing a Honda: Which Route Fits Your Lifestyle?

Deciding whether to finance or lease ultimately depends on your driving habits around Bloomington. If you want a Honda Civic to keep for a decade of commutes on Interstate 69, financing builds equity. Prefer upgrading to a new CR-V Hybrid every few years for weekend trips to Lake Monroe? Leasing pays only for depreciation, making it a smart short-term move.
| Feature | Financing a Honda | Leasing a Honda |
|---|---|---|
| Ownership | You receive the title once the auto loan is fully paid off. | The leasing company retains ownership; you return the vehicle at the end. |
| Monthly Payments | Generally higher because installments cover the vehicle’s total purchase price. | Usually lower since payments only cover the vehicle’s expected depreciation during the term. |
| Upfront Costs | Typically requires a down payment, plus standard taxes and registration fees. | Usually involves a first month’s payment, an acquisition fee, and an optional capitalized cost reduction. |
| Customization | Complete freedom to add aftermarket accessories or modify the vehicle. | Vehicle must remain in factory condition without permanent modifications. |
| Mileage | No mileage restrictions; drive as far as you need. | Capped annually (often 10,000 to 15,000 miles); overages incur a per-mile penalty. |
| Wear & Tear | You absorb the cost of dents or scratches through lower trade-in value later. | Subject to factory wear-and-use guidelines; excessive damage results in end-of-term fees. |
| End of Term | Keep driving payment-free, sell the car, or trade it in for a newer model. | Turn the keys in, purchase the vehicle for its residual value, or start a new lease. |
How Lenders Calculate Your Honda Lease and Loan Rates
Securing an auto loan or lease involves lenders evaluating a specific mix of personal financial data and vehicle details to determine your exact rates. What this means for Bloomington drivers is that locking in favorable terms leaves more room in the monthly budget for everyday life, whether you are navigating the morning commute on State Road 46 or loading up for a weekend out at Lake Monroe. If you are financing a reliable model like the 2027 Honda Civic Sedan, understanding how institutions view your application helps you structure a deal that aligns seamlessly with your lifestyle.
- Credit History Profile: Lenders pull your credit score to assess how reliably you manage borrowed money. Maintaining a strong score typically opens the door to more competitive interest rates and exclusive promotional leasing offers.
- Upfront Down Payment: Providing a larger sum at signing directly reduces the total principal you need to borrow. Because you are financing a smaller amount, your monthly obligations drop and you accumulate less interest over the lifespan of the loan.
- Length of the Contract: The duration you choose to pay off the vehicle shifts your immediate and long-term costs. For example, stretching a loan on a 2027 Honda CR-V Hybrid to 72 months instead of a standard 60-month term will noticeably lower your monthly payment, but it also increases the total interest you pay by the end of the agreement.
- Vehicle Choice and Pricing: The specific trim level, configuration, and overall sticker price of the Honda you select dictate the core loan amount. Certain new models frequently qualify for unique, manufacturer-backed financing incentives that can drastically alter the final math.
- Debt-to-Income Ratio (DTI): Banks compare your gross monthly income against your current recurring debts to ensure you can comfortably handle another payment. A healthy DTI proves to lenders that a new car won't overextend your finances as you run daily errands around College Mall.
Are There Special Honda Incentive Programs I Can Qualify For?
Yes, Honda provides several targeted lease and financing programs designed to lower your overall costs if you meet specific criteria. For example, eligible recent graduates or active-duty personnel can often access factory-backed savings when upgrading to a 2027 Honda Civic or a family-ready Pilot. What this means for drivers in Bloomington is more manageable monthly payments, potentially freeing up your budget for weekend outings at Lake Monroe or evenings out along Kirkwood Avenue. Because program requirements are strict—such as needing to prove graduation within the past two years or providing a current Leave and Earnings Statement—gathering your documentation before shopping can streamline your financing process.
- Honda College Graduate Program: If you recently earned your degree from the Indiana University campus or another accredited institution, you might be eligible for specific factory savings. To apply this offer toward a new vehicle purchase or lease, you typically need to supply a diploma issued within the past two years alongside proof of current or upcoming employment.
- Honda Military Appreciation Offer: This initiative honors active-duty U.S. military members, eligible veterans, and their spouses. Providing valid military documentation at the time of purchase can unlock reduced rates or specialized financing on new models.
- Honda Loyalty Benefits: Drivers looking to trade in an older Accord or CR-V often discover loyalty incentives waiting for them. These manufacturer rewards provide returning owners with exclusive lease terms or rate reductions on a new Honda. As resources like Edmunds often highlight, staying with a brand known for strong residual value can optimize your long-term ownership costs.
- Regional and Seasonal Promotions: Keep an eye out for dynamic offers specific to the Midwest or the greater Columbus and Greenwood areas. These rotating incentives might feature promotional APRs during holiday events or targeted lease specials on all-wheel-drive models just before winter weather impacts State Road 46.
How to Apply for a Honda Lease or Loan
Whether you are eyeing a 2027 Honda CR-V Hybrid for weekend trips out to Lake Monroe or a dependable gas-powered Civic to commute along State Road 46, securing your financing should be straightforward. Knowing what to expect means Bloomington drivers can spend less time sorting out paperwork and more time actually enjoying the drive. Here is a breakdown of the standard financing process:
- Check Your Standing: Start by getting pre-qualified online to see your likely terms and estimated interest rates. Because this step usually relies on a soft pull, you can explore your budget options without negatively impacting your credit score.
- Organize Your Paperwork: Before heading past College Mall to finalize the details, gather the necessary documentation. You will typically need a valid state-issued driver’s license, recent proof of income, proof of residence, and current auto insurance.
- Submit the Official Application: Once you lock in your chosen Honda, you will complete the formal credit application. Unlike pre-qualification, this requires a hard credit inquiry so the lender can officially approve your Annual Percentage Rate (APR).
- Review and Sign: Before taking the keys, carefully read through the contract. Confirm your monthly payment amount, the length of your term (often ranging from 36 to 72 months), and check that any added protections—such as Honda Care®—are accurately documented.
Paying Upfront vs. Financing Your Next Honda
When deciding whether to pay cash or secure an auto loan, the right choice simply depends on how you prefer to manage your liquid savings. Purchasing a vehicle like the Honda Accord Hybrid outright guarantees immediate ownership and completely eliminates interest charges over the life of the car. This approach completely frees up your future monthly income, allowing you to allocate those funds elsewhere. The main tradeoff, however, involves parting with a large lump sum all at once. Emptying a significant portion of your reserves removes those recurring bills, but holding onto that cash cushion might prove more valuable if unexpected home repairs or life events pop up down the road.
On the flip side, financing spreads the cost of your vehicle across typical contract terms of 36, 48, or 60 months. This strategy keeps your savings intact, which can also provide the flexibility to step up to a more spacious Honda Pilot for weekend camping trips in the Hoosier National Forest without draining your bank account today. For drivers navigating daily commutes down Interstate 69 or shuttling kids to Switchyard Park, what this means is striking a practical balance. You take on a structured monthly payment and applicable interest, but you preserve your financial flexibility to enjoy everything else life in Bloomington has to offer.
What Are the Pros and Cons of Each Payment Method?
Choosing the right path depends entirely on your lifestyle and how often you upgrade. For Bloomington drivers, financing builds long-term equity with zero mileage limits, while leasing typically offers lower monthly payments and constant access to the latest Honda innovations.
Pros of Financing a Honda
- Complete Ownership: Once you make that final payment, the vehicle is 100% yours to keep, sell, or hand down to a family member.
- Zero Mileage Restrictions: If you regularly commute from Bloomington to Columbus via State Road 46 or take extensive road trips, you won't have to stress about calculating daily miles to avoid overage fees.
- Unrestricted Customization: Planning weekend excursions to Hoosier National Forest? You have total freedom to permanently install aftermarket accessories, like heavy-duty roof racks on a Honda Passport, without worrying about lease return rules.
- Equity Building: Every monthly payment increases your financial stake in the car, leaving you with a valuable asset down the road.
Cons of Financing a Honda
- Higher Monthly Costs: Because you are paying for the entire total cost of the vehicle rather than just its temporary depreciation, financing generally requires a larger monthly outlay than leasing the exact same model.
- Long-Term Maintenance Responsibilities: Once Honda's 3-year/36,000-mile New Vehicle Limited Warranty expires, you take over the financial responsibility for mechanical repairs and major component replacements.
- Market Depreciation: Like all vehicles, your car will lose resale value as it ages, accumulates miles, and takes on normal wear.
Pros of Leasing a Honda
- More Affordable Payments: Since you only pay for the value the vehicle loses during your lease term, your monthly financial commitment is usually notably lower.
- Frequent Technology Upgrades: Leasing allows you to step into a brand-new vehicle—like the latest Honda Civic Sedan with updated infotainment displays and active safety features—every two to three years.
- Continuous Warranty Protection: A standard 36-month lease aligns perfectly with Honda's new-vehicle warranty, meaning major unexpected repair bills are highly unlikely during your time with the car.
- Hassle-Free Transitions: When your contract ends, you simply hand the keys back to the dealership rather than dealing with the private market or trade-in negotiations.
Cons of Leasing a Honda
- No Equity Earned: You are essentially renting the vehicle; when the lease concludes, you walk away with no ownership value or asset to sell.
- Strict Mileage Limits: Agreements typically cap annual driving between 10,000 and 15,000 miles. Exceeding this limit will trigger per-mile financial penalties at turn-in.
- Wear and Tear Penalties: Dings from tight parking spaces around the Indiana University campus or interior stains can lead to extra fees if they exceed normal use guidelines.
- Modification Limits: The vehicle must be returned in its original factory condition, meaning any personalization must be strictly temporary.
How Can You Optimize Your Vehicle Purchase?

Securing a favorable financing plan boils down to timing, preparation, and knowing your numbers. For drivers navigating daily commutes along State Road 46 or making frequent trips to the Indiana University campus, locking in a competitive 60-month APR on a 2027 Honda CR-V Hybrid directly impacts your household budget. Because Bloomington housing costs sit slightly higher than the state average, optimizing your auto loan or lease terms leaves more room for everyday expenses. Dropping an interest rate by just two percentage points on a standard vehicle loan can save you hundreds of dollars over the duration of the agreement. Here is how you can set yourself up for a streamlined and transparent process.
- Audit your credit profile: Before applying for financing, review your credit report for any inaccuracies. Disputing and removing a simple error might bump your score just enough to qualify for a lower interest tier.
- Shop your rate around: Gather loan estimates from a local Bedford or Bloomington credit union, then compare those figures against offers from the dealership. In many cases, manufacturer-backed specials provide lower promotional rates than a standard bank.
- Time your visit strategically: Honda frequently updates incentives at the end of the month, the close of a financial quarter, or when the next model year transitions into the showroom. Paying attention to these cycles can unlock seasonal financing specials.
- Focus on the base price first: Treat the actual cost of a 2027 Honda Accord independently from your trade-in equity or your desired monthly payment. Establishing the vehicle's price before discussing loan structures keeps the conversation clear and straightforward.
- Understand the critical lease terms: If you plan to lease, three factors dictate your monthly obligation: the capitalized cost (the vehicle's agreed-upon value), the money factor (the lease interest rate), and the residual value (what the vehicle is projected to be worth at lease-end).
- Use trusted valuation tools: Independent consumer sites like Kelley Blue Book and Edmunds are excellent resources for researching fair market values and estimating your current vehicle's trade-in worth before you finalize a contract.
Frequently Asked Questions (FAQs)
What should I expect during the finance process?
During the finance process, Andy Mohr Honda’s team provides a transparent, hassle-free buying experience tailored to your lifestyle around Bloomington and Columbus. We use our Mohr to Your Door program to offer no-haggle pricing and review your options clearly, whether you are financing a fuel-efficient Honda Civic for campus commutes or an all-wheel-drive Honda CR-V for trips to Lake Monroe.
How does Andy Mohr Honda ensure a transparent and comfortable process for financing add-ons?
Andy Mohr Honda ensures a transparent, hassle-free buying experience by clearly explaining all options without high-pressure tactics. Our team will review each available package with you, ensuring you only choose the features that make sense for navigating Interstate 69 or handling Bloomington's snowy winter weather.
How does Andy Mohr Honda present additional coverage and protection options in the finance office?
Andy Mohr Honda's team presents all available protection plans upfront using our transparent, no-haggle pricing philosophy. We take the time to walk you through which coverage aligns with your needs, such as ensuring your Honda Pilot is protected for weekend excursions out to Hoosier National Forest.
How does Andy Mohr Honda help you prepare for a seamless and relaxed finance discussion?
Andy Mohr Honda helps you prepare by offering our Mohr to Your Door program, allowing you to explore virtual showrooms and review pricing right from home. By the time you finalize details with our team, we have streamlined the paperwork so you can quickly get back to your errands near College Mall.
What awards has the service department at Andy Mohr Honda received?
The service department at Andy Mohr Honda has been honored with Honda’s Express Service Elite Award. Our factory-certified technicians ensure your vehicle performs at its best on State Road 46, and we provide a full suite of complimentary amenities while you wait.
How does Andy Mohr Honda support the local Bloomington community?
Since opening in 2015, Andy Mohr Honda has been deeply committed to our community by actively supporting New Hope for Families. Our family-owned dealership strives to create a welcoming environment for everyone, reflecting the friendly, vibrant culture found near Indiana University.
About Andy Mohr Honda
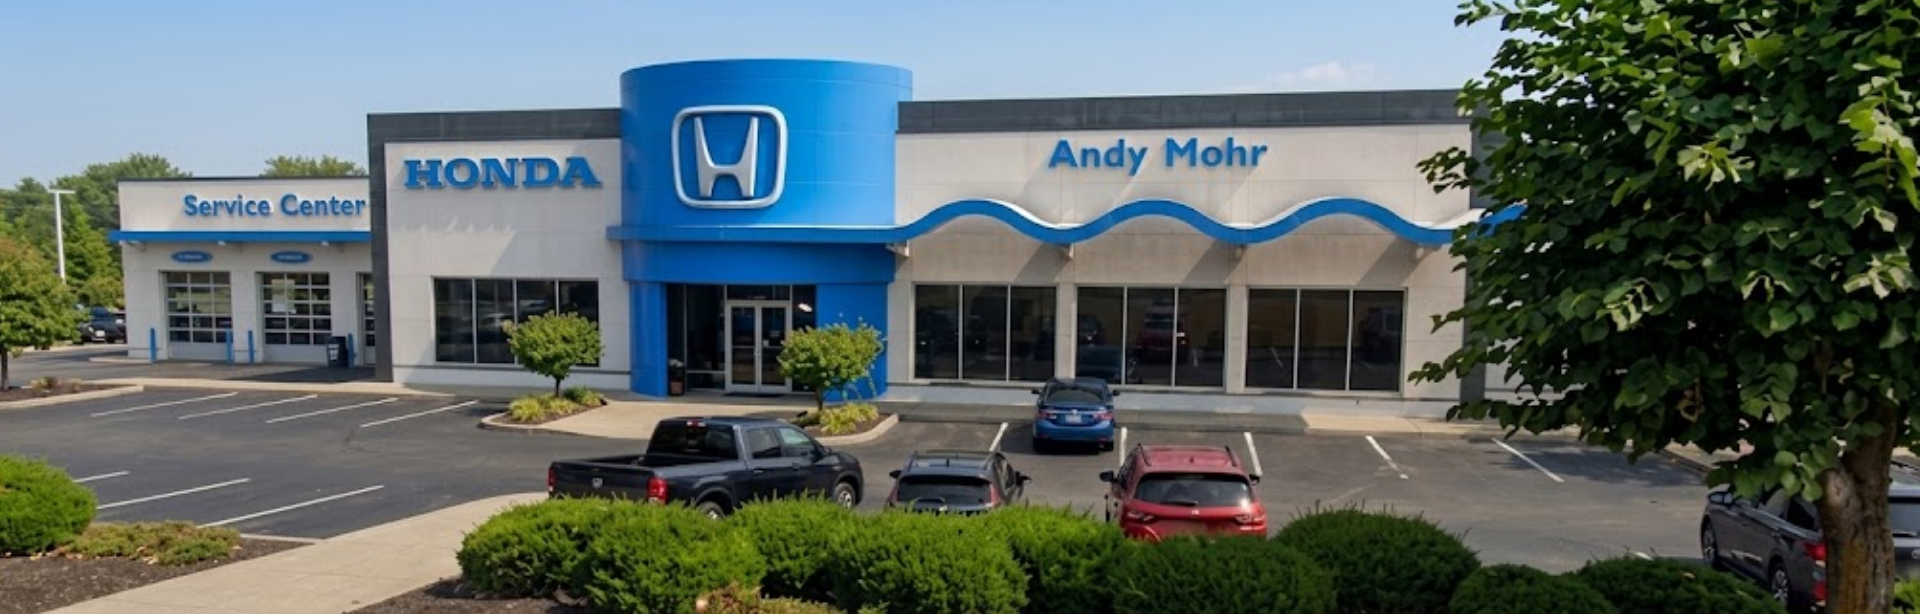
At Andy Mohr Honda, we're more than just a dealership; we're a family-owned hub for automotive excellence, proudly serving Bloomington, Columbus, and Ellettsville since 2015. Our commitment to customer satisfaction has earned us accolades like the Honda President's Award and recognition as a Carfax Top Rated Dealer. We believe in a transparent, hassle-free buying experience with our Mohr to Your Door program, offering perks like no-haggle pricing, virtual showrooms, and home delivery. Our service department, honored with Honda’s Express Service Elite Award, ensures your vehicle's top performance with factory-certified technicians and a full suite of complimentary amenities. We’re deeply committed to our community, supporting New Hope for Families, and strive to create a welcoming environment for everyone who walks through our doors.